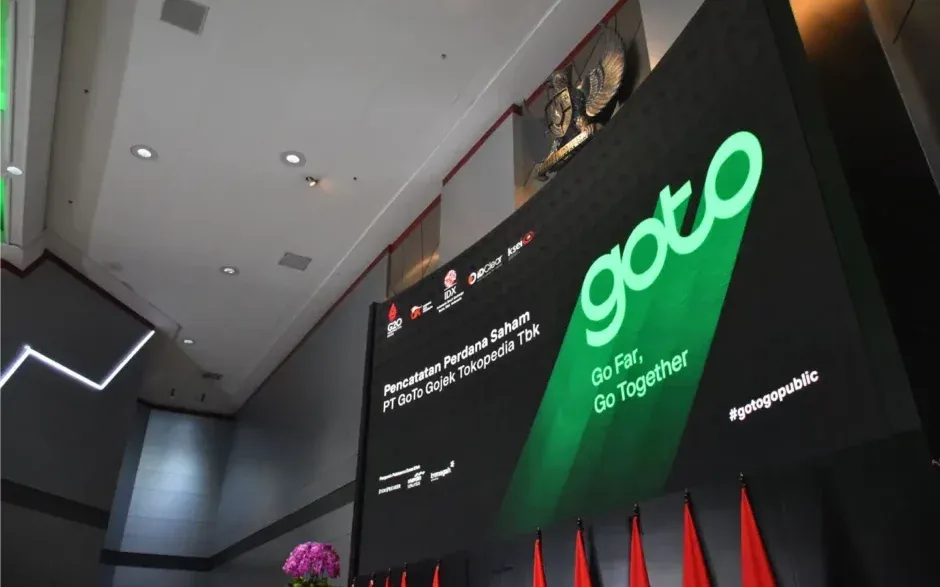
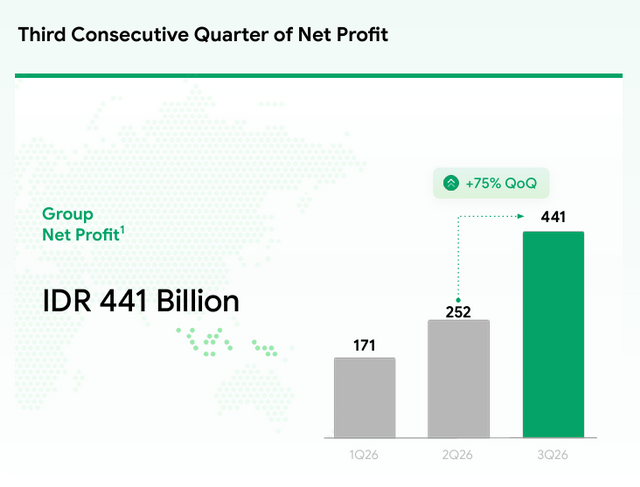
Indonesian tech giant GoTo Group posted a net profit of 441 billion rupiah ($24.3 million) in the third quarter of 2026, reversing from a loss a year earlier, even as its on-demand services (ODS) division faced pressure from Indonesia’s 8% commission cap on two-wheeler ride-hailing.
The company’s net profit compared with a net loss of 255 billion rupiah ($14 million) in the third quarter of 2025.
This marks the IDX-listed company’s third consecutive profitable quarter. Profit increased 75% quarter-on-quarter from 252 billion rupiah ($14 million) in the second quarter of 2026, following a net profit of 171 billion rupiah ($9.4 million) in the first quarter this year.
GoTo’s net revenue rose 17% year-on-year to 5.6 trillion rupiah ($308.5 million) in the third quarter, while operating profit reached 351 billion rupiah ($19.3 million), reversing an operating loss of 15 billion rupiah ($826,884) in the same period last year.
For the nine months ended September, GoTo recorded a net profit of 864 billion rupiah ($47.6 million), compared with a net loss of 997 billion rupiah ($55 million) in the same period last year. Net revenue increased 24% to 16.5 trillion rupiah ($909.5 million), while operating profit reached 1.13 trillion rupiah, reversing an operating loss of 222 billion rupiah a year earlier.
Mobility earnings face pressure
GoTo’s ODS business, which includes its Gojek mobility and delivery services, recorded adjusted EBITDA of 347 billion rupiah in the third quarter, up 3% year-on-year. However, the figure declined from 464 billion rupiah in the second quarter and 439 billion rupiah in the first quarter.
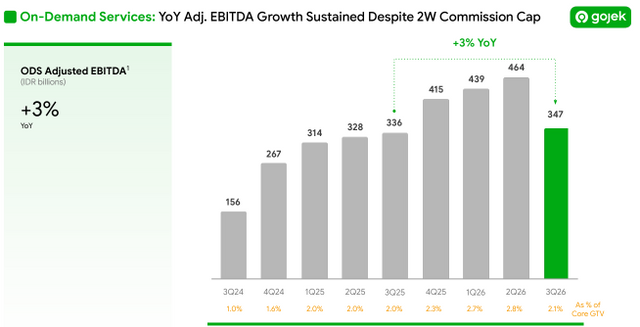
Management said the 8% commission rate that applied to two-wheeler mobility services had a significant impact on the business, affecting the performance of the division that includes GoRide and GoCar, starting in the third quarter of 2026.
In a statement, Hans Patuwo, GoTo Group CEO, said “[..] These results came during a challenging few months. It was the first full quarter since the 8% commission cap was applied to GoRide, and the impact has been significant.”
“It was the first full quarter since the 8% commission cap was applied to GoRide, and the impact has been significant.” — Hans Patuwo, GoTo Group CEO
Mobility adjusted EBITDA fell 16% year-on-year to 159 billion rupiah in the third quarter, compared with 290 billion rupiah in the second quarter and 280 billion rupiah in the first quarter.
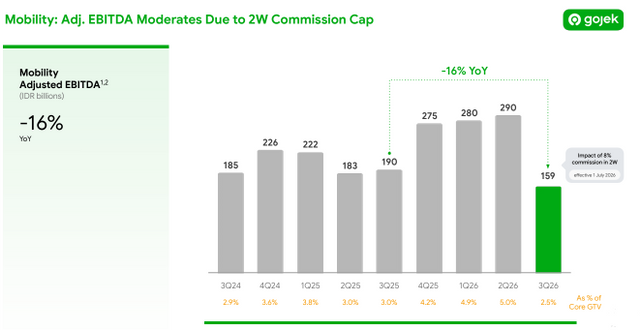
Management acknowledged the pressure but said the company had to balance the impact on its operations with its commitments to investors.
The delivery business remained profitable, with adjusted EBITDA increasing 20% year-on-year to 227 billion rupiah in the third quarter. This compared with 223 billion rupiah in the second quarter and 203 billion rupiah in the first quarter.
Across ODS, core gross transaction value (GTV) increased 1% year-on-year to 16.9 trillion rupiah, while net revenue reached 3.3 trillion rupiah.
Completed orders grew 9% on a consolidated basis, with mobility orders increasing 10% and delivery orders rising 7%.
Management said GoTo was expanding mass-market products to encourage more frequent transactions, even if individual transaction values remained relatively small.
Fintech drives earnings growth
GoTo’s fintech business Gopay recorded adjusted EBITDA of 550 billion rupiah in the third quarter, up 304% year-on-year. This compared with 481 billion rupiah in the second quarter and 364 billion rupiah in the first quarter.
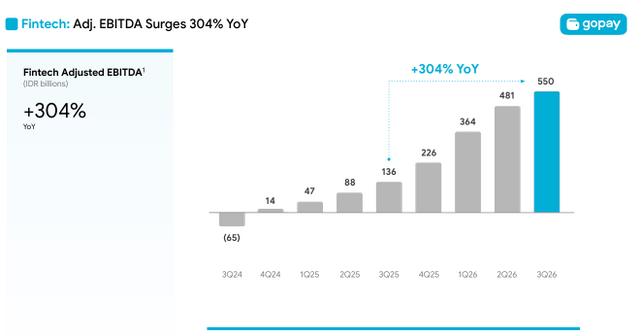
The segment’s core GTV increased 96% year-on-year to 187 trillion rupiah in the third quarter, from 130.6 trillion rupiah in the first quarter and 157.3 trillion rupiah in the second quarter. Net revenue rose 49% year-on-year.
Monthly transacting users for the fintech business grew 26% to 30.4 million, while transaction volume increased 86% to 2.8 billion.
GoTo’s outstanding loan book reached 12 trillion rupiah, up 51% year-on-year.
Management attributed the segment’s earnings growth to the combination of payments and lending within its GoPay business. The payments business generates a high volume of transactions, providing a customer base for lending products with higher margins.
The fintech business complements GoTo’s ODS operations, with growth in payments and lending contributing to the group’s overall profitability.
Across its broader ecosystem, GoTo’s annual transacting users reached 72.5 million, up 16% year-on-year, while core GTV rose 89% to 194 trillion rupiah.
The third-quarter results highlight the contrasting performance of GoTo’s two main operating segments. Fintech continued to drive earnings growth through payments and lending, while mobility profitability came under pressure amid the impact of the 8% commission rate.
Despite the pressure on mobility, GoTo raised its full-year adjusted EBITDA guidance for both the group and its fintech and ODS businesses, signalling expectations of stronger operating performance in the remainder of 2026.
The company raised its full-year 2026 adjusted EBITDA guidance to between 3.5 trillion rupiah and 3.7 trillion rupiah, from its previous range of 3.2 trillion rupiah to 3.4 trillion rupiah.
GoTo raised its adjusted EBITDA guidance for its financial technology business to between 1.9 trillion rupiah and 2 trillion rupiah, from 1.7 trillion rupiah to 1.8 trillion rupiah. Its ODS business is now expected to deliver adjusted EBITDA of between 1.4 trillion rupiah and 1.6 trillion rupiah, compared with the previous guidance of 1.4 trillion rupiah to 1.5 trillion rupiah.